by Rob Jennings | Sep 20, 2026 | Mortgage Talk
Meghan is 26. She works as an airport duty manager in St. John’s, Newfoundland. Last year, she bought a three-bedroom townhouse for $258,000.
Here’s the part worth investigating: her total monthly housing cost, including the mortgage, property taxes, home insurance, utilities, maintenance, and repairs, lands at roughly the same number she used to hand her landlord every month.
She pays no more to own than she paid to rent.
That outcome sounds like luck. It looks like luck from the outside. Trace the numbers back, and a different picture emerges.
Her monthly payment was built years before she ever called a real estate agent, through a series of decisions that are easy to skip when you’re young and renting and not really thinking about any of this yet.
This is her story, and the lessons hiding inside it.
The Assumption Worth Questioning
A lot of young renters carry one belief quietly: owning always costs dramatically more than renting, so why bother running the numbers.
The numbers tell a more complicated story. On a national level, the difference between rental costs and mortgage costs has narrowed considerably.
For condos, the average rent sits at $2,340 while the average monthly mortgage payment sits at $2,417. A difference of $77.
In a lower-cost market like St. John’s, that difference can shrink to zero or flip entirely.
Newfoundland and Labrador offers some of the strongest ownership economics in the country, with 10-year net costs of owning coming in more than $40,000 lower than renting.
Forty thousand dollars over a decade. That is the price of the assumption, left unexamined.
Meghan examined it. Here is how she got to the closing table.
The Case File: How Meghan Actually Did It
Step One: She Started Saving Before She Had a Goal
Meghan opened a Tax-Free Savings Account in her early twenties and set up an automatic transfer of $500 every month. She also built up $13,000 in a regular savings account on the side.
She did this before she knew she wanted a house. The habit came first, and the goal showed up later and found something to work with.
A PWL Capital study found that few people would willingly skip a mortgage payment to fund a vacation, yet plenty will pause their savings without a second thought. A mortgage forces the decision. A savings account waits for you to feel like it.
Meghan built the habit years before she had the goal. That put her ahead of renters waiting for the right time to start.
Step Two: She Grew Her Income on Purpose
Savings alone won’t carry you to qualification. Income does the heavy lifting there.
Meghan moved into an airport duty manager role that doubled her salary to over $40 an hour. That one move changed everything lenders looked at when they opened her file.
Homebuying advice tends to fixate on the down payment and say almost nothing about the income side of the equation.
Lenders assess both. A rising income with low consumer debt reads as a strong file, even at a young age and even on a single application.
Step Three: She Searched Like It Was a Second Job
Meghan looked at a lot of properties. She took her time. The townhouse she landed on was $258,000, comfortably within what her income and savings supported, and she didn’t push past it.
💡 Tip: A preapproval number is a ceiling, and ceilings exist so you can stand comfortably below them. Buying at the top of a preapproval leaves nothing for the furnace that dies in February.
What the Broader Data Confirms
Meghan’s story fits inside three larger shifts happening across the Canadian housing market.
- Solo buying has gone mainstream. Four in 10 Canadian renters are willing to apply for a mortgage alone. Waiting for a partner before buying has stopped being the default path.
- Single women are a rising force. In 1981, single women made up 11% of homebuyers. By 2024, that share reached 19%. Meghan stands inside a demographic shift, and ahead of it.
- Her age group leads the market. Buyers aged 25 to 34 represent 56% of homebuyers, the largest single cohort in the country.
Her timing helped too. Newfoundland and Labrador is heading into a seller’s market, with limited inventory and strong first-time buyer demand.
Rising rents keep pushing tenants toward ownership. Buying before that pressure fully arrives put her on the equity-building side of the line.
The Honest Caveats
A responsible reading of this case includes the risks. A monthly payment that matches rent today can move.
Consider what sits ahead of Meghan and any buyer like her:
- Surprise costs show up. CMHC research found that 36% of buyers ran into unexpected expenses during their purchase. Roof repairs, appliance failures, and special assessments don’t appear on a mortgage statement.
- Renewal risk is real. Her rate is locked for a term. At renewal, the market sets a new one, and her payment adjusts with it.
- A low purchase price does not equal easy ownership. The carrying cost of a home includes everything around the mortgage, and those costs demand a buffer.
⚠️ Warning: A budget that works only when nothing goes wrong is a budget that will eventually fail. Build the repair fund before you need it.
Meghan’s $13,000 side savings account exists for exactly this reason. That cushion is part of the strategy, and it deserves as much credit as the down payment.
The Real Lesson: Your Payment Is Built Years in Advance
This case study keeps pointing back to one thing.
The monthly difference between renting and owning is set less by the home’s price than by everything else a person carries into the decision.
Consumer debt, car payments, lifestyle spending, it all quietly shrinks buying power long before a lender runs the numbers. Meghan carried little of that. Her income went to savings and a pretty ordinary life, so when qualification day came, her file was clean.
That’s the adjustable part of affordability. The market sets prices. You set the obligations you bring to the table.
Shift the question from “can I afford this” to “what would I change to make this work.” You get levers: pay down a card, skip the car upgrade, redirect $500 a month, go after the promotion. Each one moves your monthly number.
How You Can Run Meghan’s Playbook
Her path translates into five moves anyone can start this month:
- Automate savings now, even without a homebuying goal. $500 a month into a TFSA builds both a down payment and a track record.
- Treat your income as a project. A raise or a career move often does more for qualification than years of extra saving.
- Clear consumer debt first. It drags on your buying power more than you’d expect.
- Compare your real rent to a real carrying cost. Include taxes, insurance, utilities, and maintenance on the ownership side, and run honest numbers for your market.
- Buy below your ceiling. The comfortable payment holds up longer than the impressive address.
You don’t need a perfect file. A solid plan and time to work it gets you surprisingly far.
Find Out Where You Stand
Meghan’s story started with one question: what would ownership actually cost her, in her market, with her numbers. She got the answer.
You can ask the same question today.
At Jennings & Associates, the team compares options from more than 20 lenders and builds a mortgage strategy around your full financial picture, in plain language and with zero pressure.
Maybe your rent payment is already a mortgage payment in disguise. There is one way to find out. Let’s talk.
by Rob Jennings | Aug 13, 2026 | Mortgage Talk
Every few months a headline asks whether the market has hit bottom. Reporters line up economists, compare forecasts, and turn a single data point into a national verdict.
I read those stories the same way you do. Then I look at the deals actually closing on my desk here in St. John’s, and the two pictures rarely match.
So let me offer a different starting point. The bottom is a spectator’s word. It matters to forecasters and headline writers. It rarely matters to the person deciding whether to buy, renew, or refinance this month.
What “Bottom” Actually Means, and to Whom
Before answering whether we’ve hit one, it’s worth being honest about what the word is actually measuring.
A market bottom is a national average. It blends Ontario, British Columbia, the Prairies, Quebec, and Atlantic Canada into one number. That number describes a country. It does not describe your street.
Canada’s national housing agency, CMHC, refuses to call bottoms at all.
Deputy Chief Economist Kevin Hughes points out that prices are likely to keep softening through 2026 before growing modestly afterward. The agency treats a bottom as something you only recognize in hindsight.
💡 A market call tells you where the country was. Your decision lives somewhere else entirely.
The National Story: Stable
The recent national numbers show a market that’s mostly caught its breath.
- National sales reached 38,014 in June 2026, up 0.5% from May.
- The composite benchmark price held flat at $657,700, the first month without a decline in 17 months.
- Inventory sat at 4.8 months, which reads as broadly balanced.
RBC assistant chief economist Robert Hogue calls this a long road ahead. He notes the June gain marks a sharp deceleration from the 5.5% jump the month before, and that transactions still sit about 12% below the ten-year average.
That reading seems fair to me. A market can stop falling without racing back up. Stability is its own kind of health, even if it doesn’t make a great headline.
Zoom In, and the Picture Changes
The national frame starts breaking down when you zoom in.
Ontario and British Columbia are still working off years of frenzy. BC’s benchmark price fell 5.0% year over year. Ontario’s dropped 4.6%. Those are the loud markets, and they are the ones still nursing a hangover.
Now look east. Newfoundland and Labrador reached record highs for both average and benchmark prices in June 2026.
The average home price rose to $375,334, up 6.1% year over year. Sales climbed 35.1% month over month to 554 transactions. Supply sits near 4.6 months, which is balanced.
The same month that produced a cautious national headline produced a record here.
Inventory remains tight across the Prairies, Quebec, and Atlantic Canada, where listings still sit below pre-pandemic levels and home values continue to appreciate.
That’s the divide I live in every day. The story on the screen describes a market you may not live in.
Why I Judge Health by Activity
People ask me if prices are going up or down. Fair question, but it’s usually the wrong first question.
A healthy market is one where transactions flow, listings and buyers find each other, and people are making moves for real reasons.
In Newfoundland and Labrador, the sales-to-new-listings ratio is 54.5% with 4.6 months of supply. Buyers and sellers are meeting in the middle.
A market that never spiked has nothing to correct. Which is why a quiet market can be sound while a noisier one is still working things out.
The Rate Picture Has Settled
One reason the frenzy has cooled is that borrowing costs stopped moving.
The Bank of Canada held its overnight rate at 2.25% for the sixth straight time on July 15, 2026.
As of August 2026, the best high-ratio five-year fixed rate is 4.04%, and the best five-year variable is 3.40%. Most forecasts expect the rate to hold through much of 2026, with the next move tilting toward a hike rather than a cut.
For you, that means the guessing game is smaller than it was two years ago. The floor on rates appears to be in.
💡 When rates stop swinging, the real constraint becomes what you actually qualify for.
The Constraint Nobody Puts in the Headline
Rates have stabilized. Prices have softened in the big markets. Buyers are still sitting on the sidelines, though, and the honest reason is qualification.
In 2026, income limits under the mortgage stress test rules are the main brake on demand. Prices remain high relative to income, and economic confidence is shaky.
At that point the national debate stops being useful. Whether the country has bottomed changes nothing about whether your income, your down payment, and your credit can carry the home in front of you.
The Question Worth Asking Instead
I can’t tell you the country has hit bottom. CMHC won’t either, and they have more data than either of us.
A better question: can your situation, in your place, carry the decision in front of you right now?
That question has a real answer. It depends on your local prices, your rate, your qualification, and your timeline. None of those live in a national headline.
You don’t need a perfect file. You need a plan that fits the market you actually live in.
Where This Leaves You
The national market looks stable and slow, and that’s fine. The loud provinces are still adjusting. The quieter ones, including this one, are in decent shape.
Waiting for a headline to declare the coast clear means letting someone else’s average decide your timeline. Your own numbers are a better guide.
If you want to know where you actually stand, in your city, on your file, let’s talk. I would rather show you your real numbers than help you guess at the country’s.
Rob Jennings, Jennings & Associates – East Coast Mortgage Brokers, St. John’s, Newfoundland.
by Rob Jennings | Aug 7, 2026 | Mortgage Talk
You are about to borrow more money than you will ever borrow again. And the first question that comes up is a simple one: do I call my own bank, or do I call a broker?
I have spent a lot of time with that question. And honestly, I think it gets answered badly more often than it gets answered well. Just through the wrong framing.
The usual frame is rate versus convenience. The broker digs up a lower number. The bank is familiar. Pick your priority and move on.
That framing skips the part that actually shapes the next few decades of your financial life.
The Real Question Hiding Underneath
Before you weigh any piece of mortgage advice, ask one thing first.
Who does this person actually work for?
When you walk into your bank, the advisor across the desk represents that bank. They are helpful, often genuinely kind, and they know their products well. Those products all sit on one shelf. Their job is to place a loan from that shelf into your hands.
A broker works differently. Their mandate is to represent you across many lenders at once. Banks, credit unions, and alternative options all compete for your file.
Read every recommendation you receive through that allegiance. It explains a lot about why two people can look at the same situation and steer you toward two different places.
Why the Headline Rate Is the Wrong Thing to Fixate On
The rate on the sticker is the number that gets quoted. It is what people text each other. It feels like the whole decision.
The rate matters. It is one line in a much longer story, and it is rarely the most expensive line.
A mortgage carries terms that shape your money for years. How much you can pay down early without a penalty. What it costs to break the loan if life changes. How the lender treats you when you want to move, refinance, or consolidate.
💡 Judge a mortgage by its whole lifetime cost and flexibility, not the single headline number.
A slightly higher rate with room to breathe often beats a rock-bottom rate that locks you in a box.
I have talked with people who saved a few dollars a month at signing and then paid thousands to break a rigid loan three years later when their circumstances shifted. The cost buried in the structure usually outweighs the rate on the front page.
Two Jobs Hiding Inside One Question
There is a quiet trick to this decision. You are really evaluating two separate things at once, and they tend to get blurred into one gut call.
One is access. How many real options can this person put in front of you?
The other is advocacy. When the terms need pushing, who is built to push on your behalf?
Worth pulling those apart and evaluating each one separately.
- Your bank gives you one lender’s answer, delivered by someone who already knows your accounts.
- A broker gives you a comparison across many lenders, delivered by someone whose only client in the room is you.
Blurring those two into one feeling is how solid borrowers end up with a loan that was fine, when it could have been genuinely good.
The Constraint That Works in Your Favor
Here is a piece of leverage that tends to get overlooked.
The party that has to fight harder to win your business often serves you better. Your existing bank already has you. A broker, and the lenders competing through that broker, have to earn you.
That competition shows up in the terms, the flexibility, and the room to negotiate. When a lender knows they are one of twenty options on your desk, the conversation changes.
One choice presented as a decision is not the same as a real decision. Count the options sitting behind any offer before you call it a good one.
When your bank hands you a renewal letter, that is one option wearing the costume of a final answer. Before you sign it, it helps to see what the rest of the market would offer for the same file.
Where Going Directly to Your Bank Makes Sense
I will not pretend one door fits every situation. Banks earn their place plenty of times.
If you have a long, strong history with your bank, they sometimes bring you an offer that reflects that relationship.
The process can feel streamlined because your information already lives in their system. For a straightforward file and a borrower who values a familiar logo, that ease has genuine worth.
Just be honest about the trade. Convenience and a familiar name cost something. You pay it quietly, in the options you never got shown.
Where a Broker Tends to Earn Its Keep
A broker shines when your situation carries any real texture.
- First-time buyers who are nervous but excited and want the whole market explained in plain language.
- Homeowners at renewal who want to compare their bank’s offer against twenty other lenders before signing.
- People refinancing or consolidating debt who need a structure built around their life, not the lender’s shelf.
- Newcomers to Canada with limited credit history who need lenders that look past a single score.
- Investors and builders who need creative structuring across several properties.
The more moving parts your file has, the more that breadth of choice matters.
Move the Hard Conversation Earlier
One thing shifts outcomes more than any rate hunt.
Have the analysis before emotion locks you into a path. Once you have fallen for a house or grown tired of your renewal deadline, the numbers get squeezed into whatever is easiest. Room to think disappears.
Sit down early. Look at the whole picture before the clock starts pressing. A calm read of the numbers beats a rushed one.
How I Would Frame the Choice
The choice comes down to whose interests the person across the table is built to serve.
That allegiance quietly decides the terms you live with for decades. It shapes the exit costs, the flexibility, and the room you have to negotiate long after the ink dries.
At Jennings and Associates, our whole reason for existing is to stand in your corner across the full market.
We compare offers from more than twenty lenders, explain every term in plain words, and build a plan around your life rather than one shelf of products.
Your Next Step
💡 Before you sign a renewal letter or accept a first offer, get a second read from someone whose only job is to represent you.
You do not need a perfect file. You need the right plan and an honest look at every option on the table.
Reach out for a free strategy call, and let’s look at your numbers together before anything gets locked in.
by Rob Jennings | Jul 25, 2026 | Mortgage Talk
The Bank of Canada put out a statement most people skimmed and then worried about.
Growth has been weak. Growth is set up to pick up.
Two lines, and depending on how you read them, they either sound like bad news or a heads-up.
You probably felt the first half more than the second. Weak growth lands at your kitchen table long before it shows up in a headline.
It looks like a tighter grocery bill, a renewal letter you’re nervous to open, and a quiet question that keeps circling in the back of your mind. Where does this leave me?
Here’s a different way to read the same statement.
A soft economy is often the price being paid on purpose
When a central bank says growth is weak but poised to improve, it’s describing two halves of one deliberate mechanism.
The slow patch isn’t the system breaking. It’s the system working.
Cooler activity is what brings inflation back down, and lower inflation is what eventually clears the way for cheaper money. The discomfort you feel now is the tool doing its job.
That reframe matters for how you plan.
Read the gloom as a timer.
A downbeat outlook, when you understand the mechanics, becomes a rough sense of how close the turn might be. The real question stops being how bad it feels and becomes how ready your own situation is when relief arrives.
I want to be honest about the limits here. Nobody can hand you the exact date or the exact size of the next rate move, and anyone who claims they can is guessing with confidence.
What history shows plainly is that these cycles bend back. They always have. The people who quietly get their position in order during the soft stretch tend to be the ones who come out ahead when it turns.
What “set up to pick up” is really doing
Pay attention to the phrasing. “Set up to pick up” suggests the groundwork is already laid. It signals a belief that current conditions carry enough momentum to recover on their own, without a dramatic new intervention.
There’s a second-order motive behind any official message. Part of the job is shaping how you feel and what you do next. A statement like this is designed to steady expectations and keep confidence intact while the slow phase runs its course.
You don’t have to take it as a promise. You can take it as a read on where we sit on the curve. And right now the read is late in the difficult part, closer to the bottom than the beginning.
The trend beneath the headline
- Weak growth is a stage, not a verdict. Economies move in cycles. A slow year is a point on a repeating pattern, and this point tends to come right before conditions ease.
- Relief usually arrives from the direction of the pain. The same softness that feels heavy now is what pulls rates down later. The scary indicator is often pointing at where the help comes from.
- Momentum takes time to show. A pickup that’s “set up” today shows up in real payments and real approvals months down the road, which is exactly why preparing early has value.
The national story and your story aren’t the same
Here’s the part that gets lost in every broad economic headline. A national statement describes an average. You don’t live inside an average.
You live in Newfoundland, or you carry a specific income, a specific renewal date, and a specific set of goals.
A broad claim about the country can be completely true and still barely move the needle where you actually stand.
Local conditions diverge from the national picture all the time. Housing demand, wages, and lender appetite look different in St. John’s than they do in a national summary.
So the useful move is to translate the macro line back down to one person. You.
Weak growth nationally doesn’t tell you what your renewal looks like. Your file, your timing, and the lenders willing to compete for it tell you that.
How to get your own position ready for the turn
If a pickup is genuinely being set up, then the smart work happens now, during the quiet part, before the crowd notices the turn.
None of this requires you to predict anything. It requires you to be ready when the direction changes.
1. Know exactly where you stand today
Get a clear picture of what you can afford and what your current mortgage is really costing you. Confidence starts with a number you can see, not a feeling you’re carrying.
2. Don’t sign a renewal out of habit
If your term is ending, the bank’s renewal letter is a starting point, not the answer. Comparing offers across more than twenty lenders often turns up a better deal than the take-it-or-leave-it rate on the page.
3. Line up your file before rates ease
When cheaper money arrives, everyone rushes at once. A file that’s clean, documented, and pre-approved ahead of time puts you first in line instead of last.
The common mistake is waiting for the “all clear.”
By the time an official message says the recovery is here, the best window for positioning has usually already passed. The advantage belongs to people who prepare during the gloom.
What this means for you
The Bank of Canada gave you a two-part message, and both parts are true at the same time. Growth has been weak. Growth is set up to pick up. Held together, they describe a mechanism moving through its slow phase toward a healthier one.
You get to decide how you hear that. As a reason to brace, or as a timer telling you the turn is closer than it feels.
The people who came out ahead in every past cycle weren’t the ones who guessed the exact bottom. They were the ones who got their own situation ready and were prepared to act the moment relief showed up.
Read the gloom as a countdown. Make sure your position is set before the clock runs out.
Where to start
If you want a straight read on where your own file sits right now, before the market shifts, that’s a conversation worth having.
No pressure, no jargon, an honest look at your numbers and your options. Let’s talk about what a plan looks like for you.
by Rob Jennings | Jul 2, 2026 | Mortgage Talk
Statistics Canada released data that should get the attention of mortgage brokers, realtors, and policy makers.
Recent immigrants are buying homes faster than before. At the same time, Canadian-born homeownership rates are going down.
The gap is widening, and the implications run deeper than most headlines show.
The Numbers Tell a Clear Story
Between 2017 and 2021, something shifted in Canadian housing.
Immigrants who got permanent residency during this period hit a 40.2% homeownership rate by their fifth year in Canada. That’s up from 35.7% in previous groups.
Canadian-born residents? Their rate dropped from 50.9% to 47.8%.
This is a fundamental change in who’s entering the housing market.
Here’s what stands out: over 85% of immigrants who owned homes within their first year had prior Canadian experience. They came as international students, temporary foreign workers, or asylum claimants first. They learned the system. They built credit. They set up income.
Then they bought.
What We’re Seeing on the Ground
In my years as a mortgage broker, I’ve watched this trend speed up.
Newcomers to Canada represent one of our five core client segments at Jennings & Associates. We’ve built specific programs to help them navigate a mortgage system that wasn’t designed with their circumstances in mind.
The challenge is real. You arrive in Canada with strong credentials, solid income potential, and genuine commitment to building a life here. But you’re missing the one thing traditional lenders want most: Canadian credit history.
Alternative lending programs fill this gap. Lenders who look beyond credit scores. Programs recognizing foreign income, education, and work experience. Strategies turning “not yet” into “here’s how.”
We’ve helped hundreds of newcomers get keys to their first Canadian home. The process works. It requires expertise, patience, and lenders willing to see the full picture.
The Hidden Risk We Need to Address
Here’s where the StatCan data gets concerning.
Newcomers are buying homes at impressive rates. But they’re also carrying higher debt loads and lower retirement savings than Canadian-born homeowners.
This creates vulnerability.
When you stretch to buy a home in an expensive market, you’re betting on continued income stability and manageable interest rates. You’re assuming the market stays strong. You’re hoping nothing disrupts your financial plan.
We saw what happened when interest rates climbed from the 2% range to 5%+ over the past few years. Mortgage renewals became financial shocks. People who qualified at stress-test rates still felt the squeeze.
Picture facing this pressure with less financial cushion, fewer established support networks, and limited experience navigating Canadian economic cycles.
The risk is real, and it’s growing.
Why This Matters for Housing Policy
Immigration is now a primary driver of housing demand in Canada.
This is what the data shows.
This shift has big implications for how we think about housing supply, affordability programs, and financial literacy support.
If newcomers are becoming a larger share of homebuyers, we need mortgage products designed for their circumstances. We need better financial education programs addressing their specific challenges. We need policy recognizing their contribution to housing demand without creating systemic risk.
We’re playing catch-up.
The temporary immigration programs bringing people to Canada are functioning as pathways to homeownership. Good for integration. Good for community building. Good for the economy.
This means we need to make sure these new homeowners have the financial stability to weather market changes.
The Regional Reality Check
Here in Newfoundland, our experience is different from the national trend.
We didn’t see the immigration-driven demand reshaping markets in Toronto, Vancouver, or Halifax. Our market stayed local. Newfoundlanders competing with Newfoundlanders.
Our market stayed stable. Average home prices in St. John’s sit around $330,000. Half the national average. A house with a yard, not a condo with a view of someone else’s balcony.
We avoided the desperation gripping other markets during COVID. We didn’t see bidding wars with 20+ offers. We didn’t see people waiving conditions to get in the door.
But that’s changing.
As housing costs soar in major centres, more people are looking east. Newcomers included. They’re finding out what locals have known for years: you can build a good life here without sacrificing financial security to own a home.
The question is whether we maintain the affordability advantage as demand increases.
What This Means for Buyers
If you’re a newcomer considering homeownership, understand this: buying a home in Canada is achievable. It requires strategy, not savings alone.
Start building Canadian credit right away. Even a secured credit card helps. Pay it off monthly. Show lenders you understand how the system works.
Document everything. Foreign income, education credentials, work experience. The more you prove, the more options you’ll have.
Don’t assume you need 20% down. Many programs work with 5-10% for qualified buyers. The key is finding lenders who understand newcomer situations.
Get pre-approved before you shop. Know what you afford. Understand your monthly payment at current rates, not the rates you wish existed.
Most importantly: don’t stretch beyond your means because you qualified. The goal isn’t buying a house. The goal is keeping it.
What This Means for Canadian-Born Buyers
If you’re watching homeownership rates decline among Canadian-born residents, you’re seeing an affordability crisis.
This isn’t about competition with newcomers. This is about housing costs outpacing income growth. This is about markets pricing out an entire generation during the pandemic boom.
The solution isn’t restricting who buys. The solution is creating more housing supply, maintaining diverse mortgage options, and getting financial literacy to everyone who needs it.
Your situation is unique. Your path to homeownership might look different than your parents’ generation. What matters is having a plan working for you.
The Bigger Picture
The StatCan data shows a housing market in transition.
Immigration is reshaping demand. Affordability is creating winners and losers based on geography and timing. Financial strain is increasing for those who bought at peak prices with minimal equity.
These trends will define Canadian housing for the next decade.
As a mortgage broker, my job is helping people navigate this complexity. Turning data into strategy. Making homeownership possible without creating financial disaster.
Honest conversations about risk. Clear explanations of options. Personalized plans fitting individual situations.
A mortgage is a 25-year commitment shaping your financial future.
The newcomer homeownership surge is real. The declining Canadian-born ownership rate is real. The financial vulnerability is real.
What we do with this information matters.
Moving Forward
If you’re considering buying a home, whether you’re new to Canada or born here, start with education.
Understand what you qualify for. Understand what you afford. Understand the risks and opportunities.
Don’t let market pressure or FOMO drive your decision. Don’t assume rates will drop soon enough to save you. Don’t stretch to the maximum because a lender says you qualified.
Build a strategy accounting for your unique situation. Work with professionals who prioritize your long-term financial health over closing a deal.
The housing market will keep changing. Immigration will keep driving demand. Affordability will keep challenging buyers.
The right approach makes homeownership achievable.
You need to know where you stand and what path makes sense for you.
At Jennings & Associates, we help both newcomers and long-time Canadians navigate the mortgage process with clarity and confidence. If you’re wondering where you stand or what options exist for your situation, let’s talk. No pressure. No confusion. Honest advice and a plan working for your life.
Call us at (709) 300-4518 or visit www.jenningsmortgage.com to book your free consultation.
by Rob Jennings | Jun 18, 2026 | Mortgage Renewal, Mortgage Talk
We’ve been watching something unfold in the mortgage market that you need to know about.
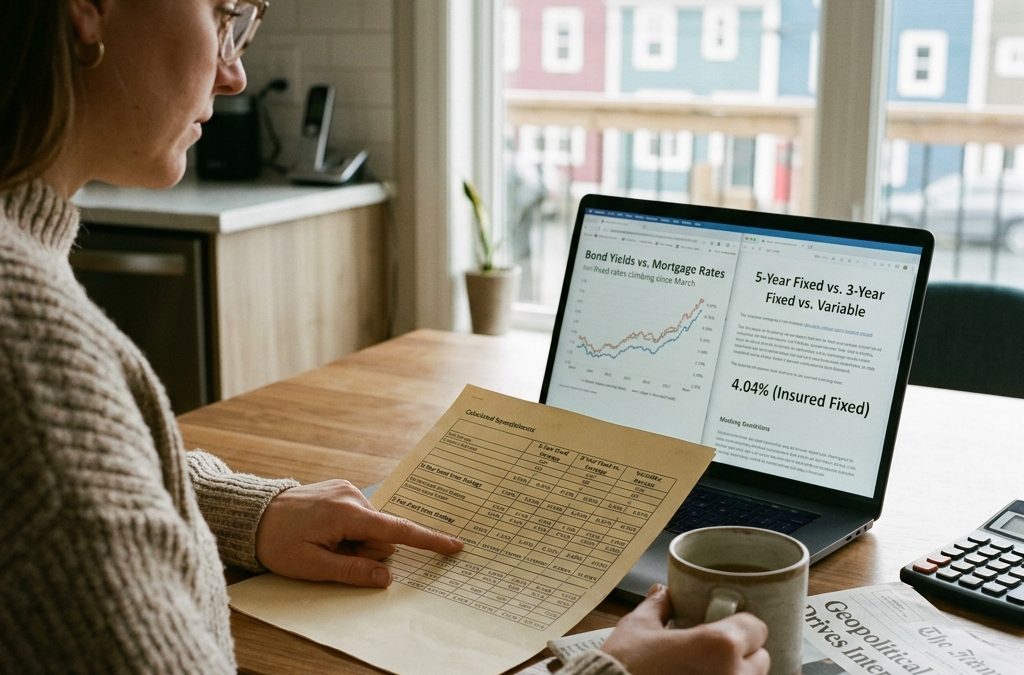
Since March, fixed mortgage rates have been climbing. Not slowly. Not quietly. They’ve jumped as much as 40 basis points in some cases.
The reason? Global uncertainty. Geopolitical tensions, especially around the Iran conflict, have rattled bond markets and stoked inflation fears. When bond yields rise, fixed mortgage rates follow.
Right now, the lowest five-year insured mortgage rate in Canada sits at 4.04%. Uninsured rates are slightly higher at 4.19%. Variable rates are lower at 3.35%, but market surveys suggest they’ll likely rise by early 2027.
So here’s the question we’re hearing more often: Should you lock in for five years, or go with a shorter term like three years?
Let’s break it down.
Why Fixed Rates Are Moving (And What It Means for You)
Mortgage rates don’t exist in a vacuum. They respond to global events, central bank signals, and how investors behave.
When geopolitical tensions rise, investors get nervous. They move money into safer assets like government bonds. The demand pushes bond yields up. And since fixed mortgage rates are tied to bond yields, lenders raise their rates.
This isn’t speculation. It’s happening right now.
Canadian lenders have already increased fixed rates by up to 40 basis points since March. That’s a noticeable shift if you’re shopping for a mortgage or coming up for renewal.
Here’s where things stand:
- Five-year insured rate: 4.04%
- Five-year uninsured rate: 4.19%
- Variable rate: 3.35%
The gap between insured and uninsured rates reflects lender risk. If you put down less than 20%, you need mortgage insurance. The protection allows lenders to offer a slightly lower rate.
But the real tension right now is between fixed and variable.
Fixed vs. Variable: The Calculation You’re Probably Running
Variable rates are cheaper today. That’s clear.
But the Q1 Market Participants Survey suggests variable rates will rise by early 2027. If you choose variable now, you’re betting rates stay low long enough for you to save money.
That’s a gamble some borrowers are willing to take. Others want certainty.
Fixed rates give you predictability. You know your payment. You know your budget. You don’t have to check the news every time the Bank of Canada meets.
But here’s the thing.
You don’t have to lock in for five years.
A three-year term might give you both stability and flexibility.
The Case for a Three-Year Fixed Term
Most borrowers default to a five-year term. It’s the industry standard. It feels safe.
But safe doesn’t mean smart.
A three-year term gives you flexibility. You lock in a rate, protect yourself from short-term swings, and position yourself to renegotiate sooner.
Here’s what this means for you:
If rates drop in two or three years, you’re not stuck in a five-year contract. You renegotiate when your term ends and take advantage of better rates.
If rates rise, you’re protected for the next three years. You have time to plan your next move.
Yes, a three-year rate might be slightly higher than a five-year rate right now. But the difference is often small. And the flexibility can be worth it.
One way to look at it:
A five-year term is like signing a long-term lease. You’re committed. A three-year term is like a shorter lease with an option to renew or move. More control.
What We’re Seeing in the Market Right Now
We work with borrowers across Newfoundland and Atlantic Canada every day. We’re seeing three common scenarios:
1. First-time buyers who want certainty
You’re stretching to afford your first home. You need to know your payment won’t change. A three-year fixed term gives you that stability without locking you in for too long.
2. Renewals who are nervous about timing
Your term is ending soon. You’re looking at rates that are higher than what you had. You’re wondering if you should wait or lock in now.
Here’s the truth: Waiting rarely works out. If rates are rising, they’ll keep rising. A three-year term lets you lock in now and reassess when things stabilize.
3. Investors who want flexibility
You’re managing multiple properties. You need to balance cash flow with strategy. A three-year term gives you the ability to refinance or restructure sooner if your portfolio changes.
All three scenarios share something: the value of flexibility.
The Hidden Risk of Waiting
Some borrowers think they can time the market. They’ll wait for rates to drop, then lock in.
That strategy assumes rates will drop. And that you’ll know when the bottom hits.
We’ve been doing this for over 18 years. We’ve never met anyone who perfectly timed the market.
Here’s what happens:
Rates rise while you wait. You end up paying more than you would have if you’d locked in earlier.
Or rates drop slightly, but by the time you act, they’ve already started climbing again.
The market doesn’t wait for you to be ready.
A three-year term removes the pressure. You lock in now. You protect yourself from short-term swings. And you give yourself a chance to renegotiate when your term ends.
What About Variable Rates?
Variable rates are lower right now. That’s a fact.
But the Q1 Market Participants Survey suggests they’ll rise by early 2027. That’s less than two years from now.
If you choose variable, you’re betting the savings you get today will outweigh the increases coming tomorrow.
For some borrowers, that bet makes sense. If you can handle payment increases, or if you plan to pay down your mortgage aggressively, variable might work.
But if you need predictability, or if your budget is tight, variable adds risk.
A three-year fixed term removes the risk. You know your rate. You know your payment. And you’re not locked in for five years.
How to Decide What’s Right for You
Every borrower is different. Your income, your goals, your risk tolerance all matter.
Here are three questions we ask every client:
1. How long do you plan to stay in this home?
If you’re planning to move in two or three years, a shorter term makes sense. You won’t pay a penalty to break your mortgage early.
2. How stable is your income?
If your income is predictable, you can handle a fixed payment. If it fluctuates, you might want the flexibility of variable.
3. How much risk are you comfortable with?
If rising rates will stress your budget, lock in now. If you can absorb increases, variable might save you money.
These aren’t trick questions. They’re the foundation of a mortgage strategy designed for your life.
What We’re Recommending Right Now
We don’t push products. We build strategies.
And right now, we’re seeing a lot of value in three-year fixed terms.
Here’s our thinking:
Rates are rising. Geopolitical uncertainty isn’t going away. Central banks are still figuring out their next moves.
A three-year term gives you protection without a long commitment. You get stability now and flexibility later.
Yes, you might pay a slightly higher rate than a five-year term. But the difference is often small. And the ability to renegotiate in three years instead of five can save you thousands.
We’ve helped over 3,400 clients across Atlantic Canada navigate mortgage decisions like this. We’ve seen what works. And we’ve seen what doesn’t.
A three-year term isn’t always the right answer. But in this market, it’s worth considering.
The Bottom Line
Fixed mortgage rates are rising. That’s not changing anytime soon.
You have options. You can lock in for five years. You can choose variable. Or you can take a middle path with a three-year term.
The right choice depends on your situation. Your income. Your goals. Your risk tolerance.
But here’s what we know: Waiting rarely works out. The market doesn’t wait for you to be ready.
If you’re coming up for renewal, or if you’re shopping for a mortgage right now, you need a strategy. Not just a rate.
We can help you build that strategy. We’ll compare rates from over 20 lenders. We’ll show you the difference between fixed and variable. And we’ll help you decide if a three-year term makes sense for your life.
You don’t need a perfect file. You need the right plan.
Let’s talk. Visit www.jenningsmortgage.com or call us at (709) 300-4518.
We’re here to help you move forward.