by Rob Jennings | Mar 11, 2026 | Mortgage Renewal, Mortgage Talk
I’ve been watching something unfold in the Canadian mortgage market. Most homeowners don’t realize it’s happening.
The turning point is here.
After two years of anxiety about mortgage renewals and payment shock, TD’s internal data confirms what I’ve been telling clients for months: by the second half of 2026, declining payments become the norm as more homeowners renew into lower rates.
This is a fundamental shift.
But here’s what concerns me. Too many Newfoundland homeowners will miss this opportunity because they’re waiting for their bank’s renewal letter instead of taking control right now.
The Payment Shock That Never Came
Remember all the headlines about massive payment increases crushing Canadian homeowners?
The reality looked different.
For five of Canada’s six largest banks, monthly payment increases landed between $106 and $200. Well below the catastrophic projections you saw dominating the news cycle.
Falling interest rates, rising household wealth, and lender flexibility softened the blow. The national home price index climbed more than 25% since early 2020, giving homeowners equity to tap if needed. Household financial assets rose 45%, including a 42% increase in liquid deposits.
Canadian homeowners proved more resilient than the experts predicted.
The mortgage arrears rate sits at roughly 0.22%. Only one in every 450 mortgage holders is more than three months behind on payments. This resilience surprised observers, especially given current mortgage rates exceed anything we saw between 2009 and 2022.
But resilience isn’t complacency.
The Massive Renewal Wave
Over 1.3 million mortgages will renew in 2026 alone.
A recent Equifax report shows over 28% of homeowners are switching to a better deal at renewal. Up about 46% from a year ago.
This shopping behavior tells us Canadians are finally taking control of their renewal strategy instead of accepting their bank’s first offer.
And they should be.
I’ve helped thousands of Atlantic Canadians navigate renewals. The homeowners who shop their renewal save significantly more than those who don’t. The difference between accepting your bank’s renewal letter and comparing 20+ lenders? Thousands of dollars over the life of your mortgage.
Two Groups, Two Very Different Outcomes
The renewal landscape splits Canadian homeowners into two distinct groups.
Group One: The Ultra-Low Rate Cohort
A Bank of Canada report shows about 40% of borrowers locked in mortgage rates during the ultra-low-rate period of late 2020 to early 2021. These households face the highest likelihood of payment increases. Peak renewals hit between Q4 2025 and Q1 2026.
If you’re in this group, you know it. Your 1.5% rate is ending, and you’re renewing into something higher.
Group Two: The Strategic Positioning Cohort
Many Canadians who renewed or got mortgages at the interest rate peak opted for shorter terms. They positioned themselves to reset at lower rates in the coming year, thanks to rate reductions from the Bank of Canada.
These actions reduced financial stability risk and gave breathing room in consumer budgets.
The question is: which group are you in, and what’s your plan?
What’s Actually Happening With Rates
The Bank of Canada decreased rates six consecutive times since June 2024.
Most economists predict the policy rate will stay at 2.25% for most of 2026. Forecasts from TD, National Bank, CIBC, RBC, and BMO all suggest rate stability at 2.25% throughout the year, depending on inflation trends.
This stability gives unprecedented predictability for renewal planning.
Here’s what this means. If you’re renewing in the next 12 to 18 months, you’re working with a relatively stable rate environment. You plan. You compare. You make strategic decisions instead of reactive ones.
But stability doesn’t mean rates will drop further. The window to lock in favorable terms is now.
The Newfoundland Advantage
Newfoundland homeowners enter this renewal wave from a position of strength.
While Toronto and Vancouver homeowners stretched themselves to the limit during the COVID bidding wars, Newfoundland avoided those desperate market conditions. We didn’t see the 20 to 30 bid scenarios that became normal in Ontario.
Our market stayed resilient during economic downturns. We zig when others zag.
The housing market in St. John’s offers the best Canadian homeownership opportunity based on affordability metrics. Our rent-to-price ratio, stable employment in oil and tech sectors, and conservative lending practices built a foundation protecting homeowners during volatility.
This matters for renewals because Newfoundland homeowners typically carry less mortgage stress than their counterparts in other provinces. You’re not overleveraged. You’re not house-poor. You have options.
Whether you’ll use them is the question.
The Reality Check: Payment Increases Are Still Real
Let me be clear about something.
While the payment shock narrative was overblown nationally, individual homeowners will still face real increases.
The Bank of Canada estimates average monthly mortgage payments could rise by 10% for 2025 renewals and 6% for 2026 renewals, compared to December 2024 levels. For five-year fixed-rate mortgage holders, monthly payments could climb by 15% to 20% at renewal.
A TD survey found nearly half of those renewing in the next year expect higher monthly payments. 57% anticipate an impact on their living situation. Of these renewers, 73% say they’ll need to cut back on spending to keep up.
This is a significant behavioral shift in how Canadians approach financial planning around renewals.
But here’s what the national data doesn’t capture: your specific situation.
Your Renewal Strategy Matters More Than National Trends
I’ve built my practice on a simple principle: mortgage strategy beats rate fixation every time.
Rate is important. But it’s a distant second to advice.
When a homeowner walks into my office worried about their renewal, we don’t start with “What rate do you get?” We start with “What are you trying to accomplish in the next five years?”
Are you planning to sell? Renovate? Consolidate debt? Buy a rental property? Send a kid to university?
Your mortgage renewal should align with your life, not just chase the lowest advertised rate.
This is where most homeowners make their biggest mistake. They accept their bank’s renewal offer because it seems reasonable, or they chase a rate they saw advertised online without understanding the terms, penalties, or restrictions.
Every mortgage product has trade-offs. Lower rates often come with higher penalties, restricted prepayment options, or inflexible terms. The best mortgage fits your situation and goals.
The Debt Service Ratio Is Improving
Here’s a data point that should give you confidence.
The debt service ratio for Canadian households dropped below its recent highs in 2023. The greatest strain on consumers has passed.
Households are spending less of their income on debt.
Aggregate mortgage payments in Canada are declining. Nationally, mortgage interest payments declined by an average of 1.7% in the final two quarters of last year. Enough relief to push total mortgage payments into contraction.
This seems counterintuitive given all the renewal anxiety, but it shows the reality. Many Canadians already renewed at higher rates in 2023 and 2024. The worst of the adjustment period is behind us for many households.
For Newfoundland homeowners specifically, our conservative lending practices and lower average mortgage balances mean we’re better positioned than most Canadian markets to weather this transition.
What You Should Do Right Now
If your mortgage renews in the next 12 to 18 months, here’s your action plan.
Start the conversation now. Don’t wait for your bank’s renewal letter. The letter typically arrives 30 to 120 days before your renewal date. Not enough time to properly explore your options.
Know your numbers. What’s your current rate? What’s your remaining balance? What are your prepayment privileges? When exactly does your term end? You need this information to have an informed conversation.
Understand your goals. Are you planning to stay in your home long-term? Do you need flexibility for potential life changes? Are you focused on paying down your mortgage faster or keeping payments low?
Shop your renewal. Your bank is one option. A mortgage broker has access to 20+ lenders, including broker-only lenders with competitive rates and terms your bank won’t match.
Think about your term length strategically. If you think rates will continue to decline, a shorter term might make sense. If you value payment stability and predictability, a longer term works better. This decision should align with your risk tolerance and financial goals.
Don’t ignore debt consolidation opportunities. If you’re carrying high-interest credit card debt or lines of credit, your renewal might be the time to consolidate into your mortgage at a lower rate.
The Opportunity Most Homeowners Miss
Here’s what I see happen too often.
A homeowner gets their renewal letter from the bank. The rate seems okay. They sign it and send it back. Done.
They made a decision worth hundreds of thousands of dollars in about five minutes.
The same homeowner will spend hours researching which TV to buy or where to go on vacation. But their mortgage renewal, the single largest financial commitment they have? Five minutes of attention.
This is the opportunity most homeowners miss.
Your renewal is a chance to reassess your entire mortgage strategy. It’s a chance to switch lenders if your current one isn’t serving you well. It’s a chance to adjust your payment structure, access equity, or restructure debt.
It’s a chance to save money and build wealth faster.
Only if you treat it like the significant financial decision it is.
Why Newfoundland Homeowners Should Feel Confident
I’ve worked in this market for over 18 years, through multiple rate cycles and economic conditions.
Newfoundland homeowners consistently show better financial discipline than the national average. You don’t chase trends. You don’t overextend. You build equity steadily.
The current renewal environment favors this approach.
You’re not desperate. You’re not overleveraged. You have time to make smart decisions.
The national mortgage renewal wave had economists worried. It’s playing out better than expected because Canadian homeowners, and Newfoundland homeowners especially, proved more resilient and strategic than the models predicted.
You have access to the same national lender network as homeowners in Toronto or Vancouver, but you’re working from a stronger foundation. Lower home prices relative to income, stable employment, and conservative lending practices give you flexibility.
Use it.
The Bottom Line
The mortgage renewal landscape in 2026 looks fundamentally different than the doom-and-gloom predictions suggested.
Payment increases are real but manageable for most homeowners. Rate stability gives planning certainty. The debt service ratio is improving. Aggregate mortgage payments are declining.
National trends don’t determine your outcome. Your situation and the decisions you make determine your outcome.
If you’re renewing in the next 12 to 18 months, you have an opportunity to save money, improve your mortgage structure, and position yourself for long-term success.
The homeowners who will benefit most from this environment are the ones who start planning now, shop their options thoroughly, and make strategic decisions aligned with their goals.
Don’t sign that renewal letter without exploring your options.
Your future self will thank you.
by Rob Jennings | Mar 4, 2026 | Mortgage Renewal, Mortgage Talk
I’ve watched the mortgage market shift more in the past 18 months than in the previous decade combined.
The Bank of Canada dropped its benchmark rate to 2.25% from a high of 5.0% in June 2024. The lowest we’ve seen since spring 2022.
You’d think everyone would jump on variable rates.
They didn’t.
The Data Tells a Different Story
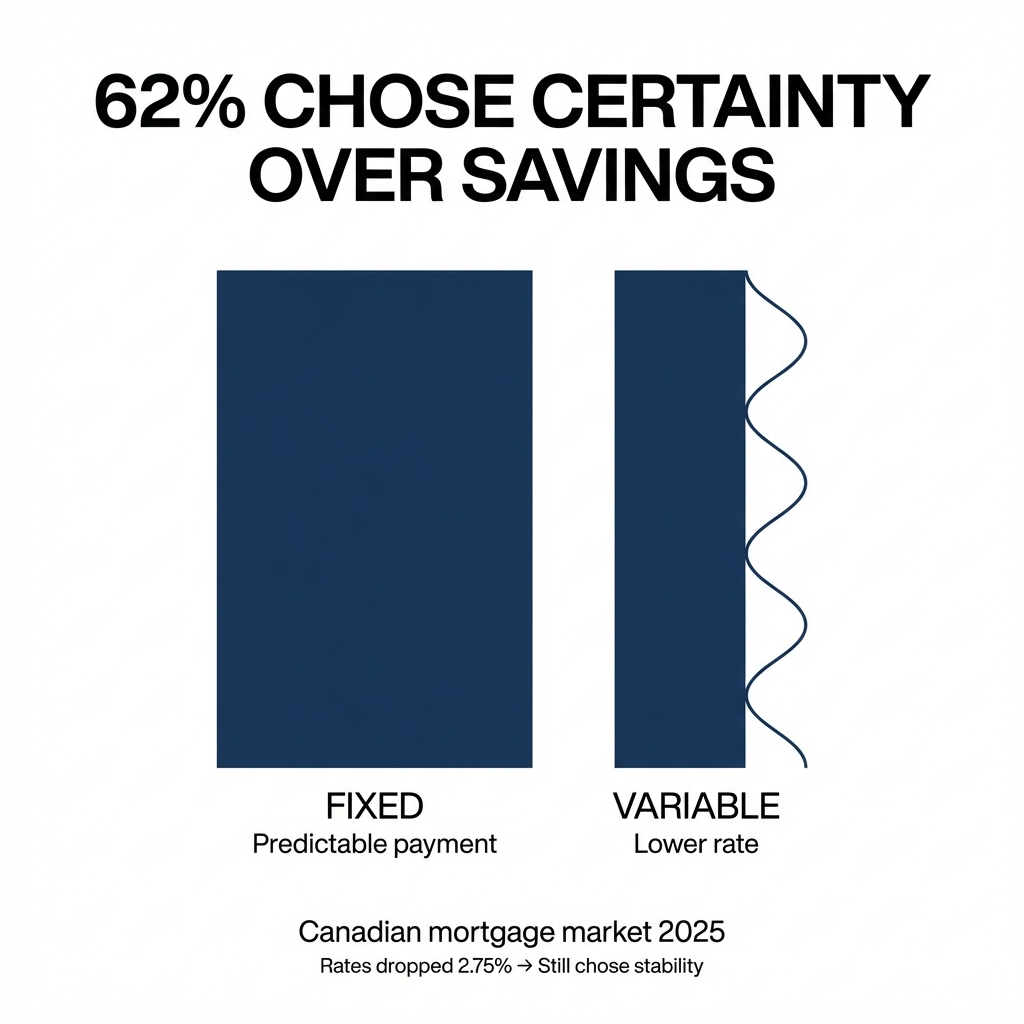
According to the 2025 CMHC Mortgage Consumer Survey, 62% of mortgage shoppers picked a fixed rate. Only 25% chose variable.
Ratehub.ca reported that 77% of all mortgage requests on its platform from January through December 2025 were for five-year fixed-rate mortgages.
Variable rates became more attractive as the Bank of Canada lowered rates through 2025. In January 2025, variable mortgages accounted for 38% of newly extended mortgages, surpassing 3 to 5-year fixed terms at 35%.
But when economic uncertainty resurfaced later in the year, borrowers shifted back. Three to five-year fixed rates reclaimed the top spot at 43%.
The pattern is clear: Canadians want payment predictability, even when variable rates offer a pricing advantage.
Why Fixed Rates Still Dominate
I talk to homeowners every day who are facing renewals. The conversation usually starts the same way.
“Rob, what should I do about my rate?”
The answer depends on what keeps you up at night.
Payment certainty matters. According to Bank of Canada research, mortgage holders with a five-year fixed rate contract renewing in 2025 or 2026 faced an average payment increase of around 15% to 20% compared with their payment in December 2024.
For a family with a $2,000 monthly payment, we’re talking about an extra $300 to $400 per month.
Fixed rates lock in that number. You know exactly what you’ll pay for the next two, three, or five years. No surprises. No budget adjustments. No stress.
Variable rates move with the market. When rates drop, your payment drops. When rates rise, so does your payment.
The stock market has historically returned an average of about 10%. For homeowners with mortgage rates below this threshold, investing may yield higher long-term returns than early payoff.
The data doesn’t capture peace of mind.
The Psychology of Mortgage Decisions
Owning your home outright is liberating. For some people, the sense of freedom is worth far more than any potential returns from investing.
I’ve seen this play out hundreds of times. A client qualifies for a variable rate at 0.5% lower than fixed. The math says go variable. They choose fixed anyway.
Because they remember 2022 and 2023. They watched friends and neighbors deal with payment shock as rates climbed. They saw the stress.
They don’t want to live that way.
The decision isn’t purely financial. It’s emotional. It’s about how you want to feel in your home.
Short-Term Fixed Deals Gain Ground
Five-year fixed mortgages were historically the most popular mortgage in Canada. Things are changing.
Shorter-term fixed-rate mortgages have gained popularity since mortgage rates jumped throughout 2022 and 2023. Three-year terms now offer buyers flexibility without locking in too long.
In the U.K., we’re seeing a similar pattern. Two-year and three-year fixed rates are becoming more competitive than five-year deals. Rates have come down from the 5% levels at the peak, and many deals are now sitting above 4%.
Major lenders including HSBC, Nationwide and Halifax kicked off the new year by reducing rates on their fixed mortgage deals to as low as 3.5%. Good news for the 1.8 million people with existing fixes due to end in 2026.
The U.K. market shows how falling rates shift borrower behavior toward shorter terms. When you expect rates to keep dropping, you don’t want to lock in for five years. You want the flexibility to refinance sooner.
The Liquidity Question
Most people overlook liquidity.
Investing money versus putting funds toward aggressive mortgage payoff maintains more liquidity. If you invest in a brokerage account and end up needing access to those funds, you withdraw them fairly easily.
Once you use funds to pay your home loan, you don’t get it back.
If you sell your home and break your mortgage, prepayment penalties would be much lower with a variable rate than a fixed rate. If your household expenses suddenly increase, you can generally swap your variable rate for a fixed rate to lock in predictability.
Your time horizon plays a big role in this decision. The longer you have, the higher the probability your investments will earn an annualized return in line with their historical averages.
That makes early mortgage payoff less advantageous for younger homeowners.
The 4% to 7% Rule
I use a simple framework with clients.
If your mortgage rate is under 4% to 4.5%, paying it off early doesn’t make sense. Anything 7% or higher and you should seriously consider making an extra payment.
The 4% to 7% range is no man’s land. Your personal circumstances and risk tolerance decide.
Two-year fixes offer flexibility for those who expect to move or refinance soon. Three or longer-year fixes provide more stability.
There’s no one-size-fits-all answer. Taxes, risk, liquidity, housing costs and psychological benefits of homeownership all factor in.
What This Means for Atlantic Canadians
Roughly 60% of Canadian mortgages were set to renew between 2025 and 2026. Mortgage decisions are now at the forefront for a massive segment of Atlantic Canadian homeowners.
Housing affordability metrics improved in late 2025. National Bank of Canada’s housing affordability monitor shows the share of household income required to cover mortgage payments declined for eight consecutive quarters, reaching its lowest level in nearly four years by Q4 2025.
Lower borrowing costs and gradual income growth drove this improvement.
But Bank of Canada officials agreed on holding the overnight rate at 2.25% earlier this month. They’re unsure whether their next policy shift will be to lower rates again or to raise them.
The uncertainty reinforces the value of strategic mortgage planning.
How to Choose Your Path
Start with these questions:
How stable is your income? If you’re in a volatile industry or self-employed, fixed rates provide a safety net. If you have a stable salary and emergency savings, you handle variable rate fluctuations.
What’s your risk tolerance? Some people sleep better knowing their payment won’t change. Others are comfortable riding the market.
What’s your timeline? Planning to move in two years? A short-term fixed or variable makes sense. Staying put for a decade? Consider your long-term rate strategy.
What’s your financial cushion? Are you able to absorb a 15% to 20% payment increase if rates rise? If not, fixed rates protect you.
What are your other financial goals? If you’re investing aggressively or building a business, keeping your mortgage payment predictable frees up mental energy for those priorities.
The Bottom Line
Variable mortgages rose in popularity in 2025 as rates fell. But fixed rates still prevail because most borrowers value certainty over savings.
The right choice depends on your personal financial situation and risk appetite. The decision isn’t purely financial. Psychological factors, such as the peace of mind from knowing your exact payment, play a significant role.
More Canadians are seeking financial stability and flexibility in an uncertain economic environment.
If you’re facing a renewal or shopping for a mortgage, don’t chase the lowest rate. Build a strategy aligned with your life, your goals, and your sleep quality.
At Jennings & Associates, we build mortgage strategies for Atlantic Canadians.
If you’re wondering where you stand, let’s talk.
by Rob Jennings | Nov 26, 2025 | First Time Home Buyers, Mortgage Renewal, Mortgage Talk
Unlocking the Local Advantage: How Newfoundland Expertise Enhances Your Mortgage Experience
Most mortgage advice misses one key fact: local knowledge matters. When you tap into Newfoundland mortgage expertise, you’re not just getting numbers—you’re gaining insight that fits your community’s unique market. Jennings & Associates offers mortgage solutions shaped by years of experience right here in Newfoundland and Labrador, making your home financing simpler and clearer. Keep reading to see how this local edge can ease your next mortgage step. Learn more about the importance of local expertise here.
Local Expertise in Mortgage Solutions
Understanding the local market is crucial when navigating the mortgage landscape. With Newfoundland’s unique challenges and opportunities, having a partner like Jennings & Associates can make all the difference.
Understanding the Newfoundland Market
Newfoundland’s housing market has its own rhythm and nuances. Whether you’re eyeing a cozy St. John’s townhouse or a sprawling property in the countryside, knowing the local ins and outs is invaluable. The region’s distinct climate and cultural factors can impact property values and buying trends. This means what works in Toronto might not apply here.
Most buyers believe any broker can secure a good deal, but local expertise is irreplaceable. Jennings & Associates knows Newfoundland’s housing patterns, providing you insights others might miss. With over 16 years of experience, they navigate local regulations and lender preferences with ease. This article discusses how location impacts mortgage options.
Tailored Home Financing Solutions
Everyone’s dream home looks different, and so should their mortgage plan. Jennings & Associates offers solutions designed for you. They look beyond the numbers, considering your personal and financial goals. By understanding your needs, they find options that traditional banks might overlook.
Imagine buying your first home with guidance that steers you clear of common pitfalls. Jennings & Associates ensures you have choices, from the lowest rates to the best terms for your situation. This personalized approach means you don’t just get a mortgage—you get peace of mind.
Enhancing Your Mortgage Process
Embarking on a mortgage journey can be daunting. But with the right support, it becomes a path of empowerment and clarity. Let’s explore how Jennings & Associates streamlines this process.
Simplifying Your Mortgage Journey
Your mortgage journey shouldn’t feel like a maze. With Jennings & Associates, it’s a straightforward path. They break down complex terms and processes, making them easy to understand. This clarity helps you make informed decisions every step of the way.
Consider the stress of juggling multiple lender offers. Jennings & Associates simplifies this by comparing them for you. They ensure you understand each option’s pros and cons. Most people think more choices mean better outcomes, but without guidance, it can lead to confusion. The team at Jennings ensures you’re not overwhelmed but empowered.
Personalized Support and Guidance
Mortgages are more than just rates—they’re about relationships. Jennings & Associates offers a personal touch, guiding you with a steady hand. You’re never just a number; you’re part of their community. They listen, advise, and support you, treating your journey as their own.
When questions arise, their team is ready to assist. Imagine having someone to turn to, who knows your financial landscape inside out. This personalized support transforms what could be a stressful experience into a collaborative process. The longer you wait to seek expert help, the more complex things can become, so reach out today.
Why Choose Jennings & Associates?
Choosing the right partner in your mortgage journey can change everything. Let’s see why Jennings & Associates stands out.
Community-Focused Mortgage Services
Jennings & Associates isn’t just about transactions; they’re about community. Deeply rooted in Newfoundland and Labrador, they understand local values and priorities. This connection means they care about your outcomes, not just their bottom line.
Their community focus extends beyond mortgages. They invest in local initiatives and support regional growth. Most people think big banks offer more stability, but with Jennings, you’re not just a client—you’re part of a broader mission. Join the discussion on community-focused mortgage services in our group.
Trustworthy and Reliable Expertise
Trust is earned, and Jennings & Associates has done so over years. Their reputation for reliability is built on consistent results and satisfied clients. When you work with them, you know you’re in capable hands.
This expertise isn’t just theoretical. It’s proven through awards and national recognition, underscoring their commitment to excellence. When you choose Jennings, you’re aligning with a team that values integrity and transparency above all. For a supportive and informed mortgage experience, consider Jennings & Associates your go-to experts. Explore the community’s thoughts on reliable mortgage advice.
Jennings & Associates stands as a beacon of trust and expertise in the Newfoundland mortgage landscape. As you contemplate your next steps, remember that local knowledge can simplify and enrich your mortgage experience. With Jennings & Associates, you’re not just securing a loan—you’re investing in a partnership for success.
by Rob Jennings | Nov 24, 2025 | Mortgage Renewal
Last week, a client walked into my office frustrated.
She’d been banking with the same institution for 15 years. Excellent credit. Stable income. When her mortgage came up for renewal, her bank sent the standard letter with a rate offer.
She assumed it was competitive.
It wasn’t.
After comparing 20+ lenders, we found her a rate that would save $10,000+ over five years. Same mortgage. Different lender.
This happens more often than you’d think.
The Question Everyone Asks
Should you go with a major bank or a smaller lender for your mortgage?
I tell every client: the question misses the point.
You don’t need to choose between big or small. You need visibility across the entire market. Because when you walk into your bank branch, you see one option. When you work with a broker, you see 20+.
The difference is huge.
What Most People Don’t Know About Smaller Lenders
When I mention alternative lenders to clients, I often hear the same concern: “Are they safe?”
Fair question.
Most smaller lenders are multi-billion dollar institutions. They’re Schedule A banks regulated by OSFI. Many are backed by CMHC. Big banks fund these smaller lenders through investments.
Your mortgage from a smaller lender? There’s a good chance RBC or TD is backing the funds.
Stability isn’t the issue. The difference is how they compete.
Why Smaller Lenders Often Beat the Big Banks
Smaller lenders need to be aggressive to gain market share. They compete on three things:
Better rates. To win business from the Big Six, smaller lenders offer something better. As of early 2025, major banks averaged around 4.64% on 5-year fixed rates. Some smaller lenders offered rates as low as 3.79% for insured mortgages.
Better prepayment privileges. Broker-only lenders offer strong prepayment options. You pay down your mortgage faster without penalty. Big banks? They’ve moved away from flexibility.
Lower penalties when life happens. Here’s something I emphasize with every client: bigger the bank, bigger the penalty.
When TD Bank slashed its posted rates in 2025, borrowers who expected a $5,400 penalty owed over $22,000. Big banks calculate penalties using inflated posted rates instead of contracted rates.
Smaller lenders typically use actual rates. The difference could be $15,000 or more.
The Insured Mortgage Advantage
If you’re putting down less than 20%, smaller lenders become even more attractive.
CMHC-insured mortgages reduce lender risk. Smaller lenders securitize these mortgages and sell them on the back end. They don’t carry the mortgage on their balance sheet, so they offer more aggressive rates.
The numbers tell the story. Borrowers are finding better options beyond the Big Six. Mortgage Finance Companies and alternative lenders have grown steadily across Canada, giving homebuyers more choices than ever.
What Banks Do Well (And Where They Fall Short)
I’m not here to bash banks. They serve a purpose.
If you want convenience and you’re banking there, walking into a branch feels easy. If you have complex business banking needs tied to your mortgage, keeping everything under one roof makes sense.
But here’s what banks do that frustrates me:
They treat new clients better than existing ones. That renewal letter you get? It’s rarely their best offer. They’re counting on inertia.
They push the five-year fixed rate as a one-size-fits-all solution. Sometimes a three-year makes more sense. Sometimes variable does. Banks love the five-year fixed because it’s more profitable for them.
They identify mortgages by interest rate alone. But your mortgage includes prepayment privileges, penalty calculations, portability options, and dozens of other features that affect your financial flexibility.
The Information Gap That Costs You Money
You don’t know what you don’t know.
When you only deal with your bank, you have no idea if their offer is competitive.
Except this isn’t a $100 purchase. This is hundreds of thousands of dollars.
According to Mortgage Professionals Canada, 45% of first-time homebuyers now use a mortgage broker. They report higher satisfaction than those who went directly to lenders. Brokers are becoming the provider of choice across Atlantic Canada.
When you walk into a single bank branch, you see one lender’s products. When you work with a broker, you see options from 20+ lenders across the entire market.
What a Comprehensive Mortgage Conversation Looks Like
When clients come to me, I don’t have a favorite bank. My favorite changes based on what each lender offers this week.
Every situation is different. You might be buying your first home or your tenth. You could be putting down 5% or 30%. You might be refinancing, renewing, or building from scratch.
A good mortgage conversation covers:
Rate options across 20+ lenders. Not just one bank’s offer.
Fixed versus variable analysis. Based on your risk tolerance and financial goals.
Term length strategy. Three-year versus five-year depends on your situation.
Prepayment privileges. How much can you pay down early? What are the limits?
Penalty calculations. If you need to break your mortgage, what will the cost be?
Your long-term plan. Are you staying in this home? Upgrading in three years? Building equity for investment properties?
The rate is important. The rate matters less than getting the right mortgage strategy for your life.
The Second Opinion
I encourage every person I speak with to get a second opinion. Get a third opinion.
You’re making a financial decision worth hundreds of thousands of dollars. Do your diligence.
If your bank has the best offer, you’ll sleep easier knowing you checked. More often, you’ll save thousands by looking beyond your branch.
The client I mentioned at the start? She got her second opinion. She saved over $12,000. She told me she wished she’d done this years ago.
You don’t need perfect credit to get a great mortgage. You don’t need to be a financial expert.
You need to know what’s available.
What This Means for You
If you’re renewing your mortgage, don’t sign the letter until you’ve compared the offer.
If you’re buying your first home, talk to someone who can show you options across the entire market.
If you’re refinancing or consolidating debt, understand that smaller lenders often have more flexibility than big banks.
The mortgage market has changed. Outstanding non-bank residential mortgages grew from $338 billion in Q3 2020 to $401 billion in Q3 2024. That’s a 19% increase.
More borrowers are learning what I’ve known for years: the best mortgage isn’t at the biggest bank.
The best mortgage is wherever you find the right combination of rate, terms, and flexibility for your situation.
You won’t find the answer by looking in only one place.
by Rob Jennings | Nov 17, 2025 | Mortgage Renewal
Navigating Your Mortgage Renewal: A Comprehensive Guide
Mortgage renewal can feel like a maze filled with confusing terms and tight deadlines. You want to secure the best deal but don’t know where to start. This guide breaks down the renewal process step-by-step and shows how Jennings & Associates offers local expertise and competitive rates tailored to your needs. Keep reading to take control of your Newfoundland mortgage renewal with confidence. For more information, you can check this mortgage renewal guide.
Understanding Mortgage Renewal
Stepping into the world of mortgage renewal can seem daunting, but it doesn’t have to be. Let’s break it down to make the process smoother for you.
Basics of Mortgage Renewal
When your current mortgage term ends, you’ll need to either pay off your remaining balance or renew your mortgage for another term. Most homeowners choose renewal. This allows you to adjust your mortgage agreement to better suit your current financial situation.
A key point is that renewal is your opportunity to renegotiate terms. This can include the interest rate and payment schedule. You don’t have to stick with your current lender; shopping around may offer better terms. Why limit yourself to one option when choices abound? Remember, your needs may have shifted since you first got your mortgage. Now is the time to ensure your mortgage still fits your life.
Key Renewal Deadlines
Timing is crucial in the mortgage renewal process. Lenders typically send a renewal notice about 120 days before your term ends. This is when you should start considering your options. Don’t let this window slip by—missing it could mean automatic renewal at less favorable terms.
Acting early gives you a head start in negotiating better rates and terms. Waiting until the last minute can limit your options and increase stress. Consider making a checklist of what to review during renewal. For more tips on preparing for renewal, visit this guide.
Benefits of Personalized Mortgage Solutions
Now that you understand the basics and deadlines, let’s explore why personalized mortgage solutions are vital.
Competitive Rates for Your Needs
Personalized mortgage solutions mean more than just custom terms—they mean better rates. By tailoring your mortgage to your unique situation, you can secure rates that align with your financial goals. Why settle for generic when you can have specific?
Jennings & Associates pride themselves on offering competitive rates that beat the standard offerings of many traditional banks. Their access to a variety of lenders means more options for you, ensuring that your mortgage renewal is as cost-effective as possible.
Expertise in Newfoundland Mortgage
Navigating the Newfoundland mortgage market requires local expertise. Here’s where Jennings & Associates excel. Why trust someone far away when you can have local experts?
Their deep understanding of Newfoundland’s market nuances provides you with insights you won’t find elsewhere. This local expertise ensures that your mortgage renewal not only meets your needs but also takes into account regional market conditions that could affect your financial future. Interested in more insights on local mortgage trends? Check out this article.
Choosing Jennings & Associates
You’ve learned about the benefits of personalized solutions—now it’s time to see why Jennings & Associates should be your go-to choice.
Simplified Renewal Process
Jennings & Associates make the renewal process straightforward. They guide you through each step, making what could be a complex procedure feel effortless. Why struggle alone when help is available?
Their team will handle the heavy lifting—comparing rates, negotiating terms, and ensuring you get the best deal possible. This not only saves you time but also provides peace of mind, knowing your mortgage is in good hands.
Local Expertise and Support
Choosing a local expert means more personalized service and support. Jennings & Associates understand the importance of community connection. Why choose faceless corporations when you can have community-focused service?
Their commitment to Newfoundland’s residents is evident in the tailored advice and support they offer. With Jennings & Associates, you’re not just another client; you’re a valued member of the community they serve. Experience the difference in service and results with a team dedicated to your success.
In summary, renewing your mortgage is a chance to improve your financial situation. With the right guidance and local expertise, you can secure a deal that suits your needs perfectly. Jennings & Associates offer the personalized service and competitive rates you deserve. Take the first step towards a better mortgage renewal today.
by Rob Jennings | Jun 24, 2025 | Mortgage Renewal, Mortgage Talk
Understanding Mortgage Renewal and Its Importance
Mortgage renewal—a term that might sound as thrilling as watching paint dry, but here at Jennings & Associates – East Coast Mortgage Brokers, we see it as a golden opportunity. Picture this: you’ve been diligently paying off your mortgage, and the end of your term looms on the horizon like a beacon of potential savings. Renewal time is your chance to renegotiate the terms of your loan, potentially lowering your interest rate, and saving you a small fortune—money that could be better spent on life’s luxuries, like a trip to a sunny beach or a new espresso machine.
Why should you care about mortgage renewal? For starters, it’s about getting the best darn rate possible. Banks tend to offer a “take it or leave it” proposition, but with our strategic approach, we ensure you’re not just a number in a queue. We have the knack for sniffing out the best deals, thanks to our vast network and insider knowledge. Our expert brokers at Jennings & Associates know that the devil is in the details, and we leave no stone unturned in our quest to secure the most competitive rates for our clients.
Renewal isn’t just a business transaction at Jennings & Associates; it’s a strategic maneuver in the grand chessboard of your financial life. We believe in turning the mundane into magnificent, ensuring that your mortgage renewal is not just another item to check off your list but a transformative moment in your home-owning journey. So, don’t let your bank’s first offer be your last stop. Partner with us, and let’s flip the script on mortgage renewal together. After all, a penny saved is a penny earned, and at Jennings, we make sure you earn plenty.
Factors Influencing Mortgage Rates in Canada
In the thrilling arena of Canadian real estate, understanding what makes mortgage rates tick is akin to having a treasure map to financial success. At Jennings & Associates, we don’t just play the game; we redefine it, crafting strategies that turn the ordinary into extraordinary savings for our clients. But what exactly influences these elusive mortgage rates?
First off, let’s dive into the economic indicators. Inflation rates, employment figures, and economic growth collectively set the stage. When the economy sizzles, so do interest rates—rising to keep inflation in check. Conversely, a cooling economy might just open the door to lower rates, setting the perfect scene for savvy buyers.
Then there’s the role of the Bank of Canada. Its overnight rate is the silent puppeteer behind lenders’ interest rates. A nudge up or down sends ripples through the mortgage world, impacting everything from fixed rates to variable loans.
On a more personal note, your credit score also steps into the spotlight. A sterling credit rating can unlock doors to the most alluring rates, while anything less might require a little more finesse—and that’s where our expertise shines. At Jennings & Associates, we turn credit challenges into opportunities, ensuring that every client is positioned for success.
Lastly, the type of mortgage you choose can steer your rate destiny. Whether it’s a fixed-rate offering stability or a variable rate for those who like to dance with market fluctuations, the choice is yours. And with our guidance, it’s a choice made with confidence.
In a world where rates rise and fall like ocean tides, Jennings & Associates stands as your lighthouse. Our team is dedicated to demystifying these factors, ensuring you’re not just informed but empowered in your mortgage journey.
How Mortgage Brokers in St. John’s Can Help
In the vibrant heart of St. John’s, where the salty Atlantic breeze carries tales of old mariners, there exists a beacon for homebuyers navigating the intricate waters of mortgage rates. Enter Jennings & Associates – East Coast Mortgage Brokers, the swashbucklers of the financial seas, armed with the expertise to secure the best mortgage rates for you. Imagine them as your financial compass, steering you away from the rocky shoals of high rates and into the calm harbor of affordable loans.
Working with a mortgage broker like Jennings & Associates isn’t just about securing a loan; it’s about crafting a strategy that aligns with your financial dreams—be it a cozy bungalow or a sprawling estate. With a keen eye for detail and a knack for negotiation, their team dives deep into the ocean of lending options, surfacing with treasure chests full of competitive rates that banks might only dream of offering. They believe in transparency and hold your hand through each step, ensuring no hidden fees or unexpected swells ruin your voyage towards homeownership.
Their bold approach is matched by a witty demeanor that turns the complex world of mortgages into a tale of adventure. Jennings & Associates not only works for you but with you, crafting a partnership as strong as the bonds of Newfoundland’s community spirit. If you’re ready to embark on the journey of buying a home, let Jennings & Associates be your guide. Trust them to navigate the financial waters with skill and precision, ensuring your home-buying experience is memorable for all the right reasons.
Strategies to Secure the Lowest Mortgage Rate
Welcome to the battlefield of mortgage rates, where every percentage point counts and victory belongs to those who strategize. At Jennings & Associates – East Coast Mortgage Brokers, we’re a seasoned platoon, marching alongside you with precision and wit, ensuring your mortgage journey is both triumphant and rewarding. Here’s how we slice through the fog of financial war to secure the lowest mortgage rates in Canada.
Harness the Power of Market Knowledge
In the realm of mortgage rates, knowledge isn’t just power—it’s your secret weapon. Our team stays ahead of the curve, monitoring market trends like hawks. We dive deep into the intricacies of interest rates, economic indicators, and market forecasts to keep you informed and empowered. With Jennings & Associates, you won’t just navigate the market—you’ll conquer it.
Customized Mortgage Strategies
No two borrowers are alike, and neither should their mortgage strategies be. We don’t just offer you a one-size-fits-all approach; we craft personalized plans that fit your unique financial footprint like a glove. Whether you’re a first-time homebuyer or a seasoned property investor, we tailor solutions that cater to your distinct needs and long-term goals.
Negotiation: The Art of the Deal
Negotiation isn’t just a skill—it’s an art form. At Jennings & Associates, we’re the Michelangelo of mortgage negotiations. With over 16 years of experience in the industry, we leverage our deep connections and reputation to negotiate fiercely on your behalf. We ensure you get the best rates possible, turning potential obstacles into stepping stones.
So, whether you’re a rookie in the mortgage game or a veteran homeowner, our strategies are designed to lead you to victory. With Jennings & Associates, your mortgage isn’t just a transaction—it’s your first step in building a financial fortress. Ready to take charge? The path to the lowest mortgage rates in Canada starts here.
The Role of Jennings & Associates in Your Mortgage Renewal
When it comes time to renew your mortgage, having the right team in your corner makes all the difference. Jennings & Associates, based in St. John’s, NL, brings over sixteen years of experience helping homeowners secure competitive rates and smarter terms—saving clients thousands over the life of their mortgage.
Instead of simply accepting your lender’s first renewal offer, Jennings & Associates helps you explore your full range of options. Their team compares multiple lenders to ensure you’re getting the most value—whether that’s a lower interest rate, more flexible terms, or a product better suited to your long-term goals.
More than just rate-shoppers, Jennings & Associates take a strategic, client-first approach. They’ll assess your current situation, future plans, and risk tolerance to recommend a renewal strategy tailored specifically to your needs. The result? A mortgage solution that aligns with your life—not just your loan.
If your renewal is coming up, this is your opportunity to take control and make your mortgage work harder for you. Let Jennings & Associates guide you through the process with expert advice and personalized service every step of the way.